What is the structural definition and industrial scope of the Gas Mixtures Market?
Our research shows that the Gas Mixtures Market represents a foundational industrial sector valued at 51.91 Billion in 2026. This market encompasses proprietary blends of atmospheric, rare, and specialty gases utilized across metallurgy, semiconductor fabrication, and advanced life sciences. Industry significance lies in enabling precise chemical reactions, calibrations, and medical therapies that unyielding standards demand.
Structural Growth Drivers and Market Restraints
The market is propelled by surging demand in semiconductor manufacturing and stringent environmental compliance mandates enforced by agencies like the EPA. However, growth faces severe headwinds from cryogenic liquid shipping bottlenecks and volatile raw material costs for rare gases like krypton and xenon. Logistical complexity remains a primary constraint for regional distributors.
The Shift Toward High-Purity Specialty Blends
Industry trends reveal a pronounced migration toward ultra-high-purity calibration gas mixtures and electronic-grade specialty formulations. Key market shifts indicate that semiconductor fabs requiring sub-nanometer etching tolerances drive heavy adoption of advanced gas blends, favoring technology innovators capable of sub-part-per-billion analytical certification.
How did the pandemic alter the trajectory of the Gas Mixtures Market?
The COVID-19 pandemic severely disrupted medical oxygen mixtures and industrial supply chains, accelerating structural shifts toward localized digital telemetry and automated inventory management. Post-pandemic recovery has been robust, driven by accelerated healthcare modernization and resilient industrial re-tooling across major manufacturing corridors globally.
Competitive Benchmarking and Market Concentration
The Gas Mixtures Market industry trends highlight high market consolidation dominated by Tier-1 industrial gas titans. Enterprises like Linde PLC, Air Liquide S.A., and Air Products and Chemicals Inc. leverage proprietary air separation technology and extensive merchant liquid distribution networks to maintain formidable competitive moats against regional players.
Executive Summary of the Gas Mixtures Market Report
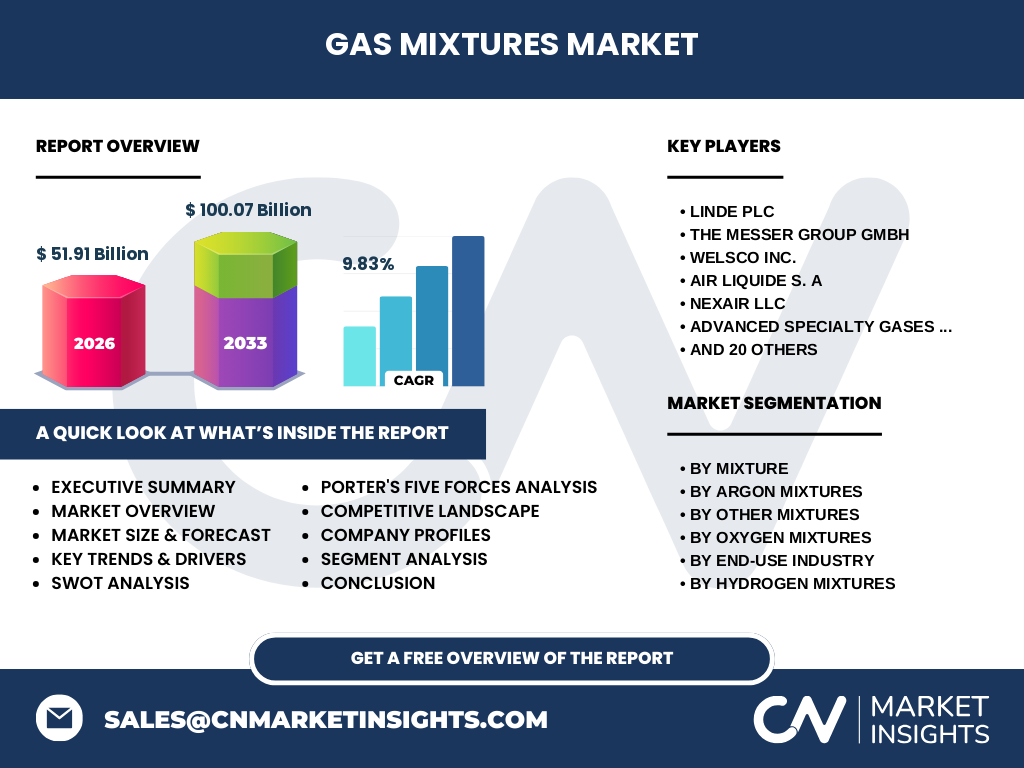
Our executive analysis projects the Gas Mixtures Market size to expand from 51.91 Billion in 2026 to 100.07 Billion by 2033, achieving a stellar CAGR of 9.83%. This dynamic expansion is heavily underpinned by rapid technological advancements in metal manufacturing, healthcare, and electronics end-use sectors.
Gas Mixtures Market Forecast 2027 to 2033
Driven by robust demand across emerging industrial economies, our forecast indicates the market will surge at a CAGR of 9.83% to reach 100.07 Billion by 2033. This trajectory reflects sustained capital expenditure in hydrogen production technology and high-purity rare gas mixtures.
Segmentation Analysis of the Gas Mixtures Market
Market segmentation spans mixture types including oxygen, nitrogen, carbon dioxide, argon, hydrogen, and specialty variants. End-use industries comprise metal manufacturing, chemicals, healthcare, electronics, and food and beverage. Distribution occurs via cylinder, merchant liquid, and tonnage channels, each serving distinct volume and purity requirements.
Geographic Distribution and Regional Performance
Regional performance highlights Asia-Pacific as the dominant manufacturing engine, fueled by extensive electronics and metal fabrication hubs in countries like Japan, South Korea, and China. North America and Europe follow closely, prioritizing stringent medical compliance and advanced research and development gas mixtures.
In-Depth Regional Review of Key Geographies
In North America, strict OSHA and FDA guidelines dictate rigorous standards for medical and environmental gas mixtures. Meanwhile, the Asia-Pacific region capitalizes on massive infrastructure investments, driving high volume consumption of industrial oxygen and nitrogen mixtures across rapidly expanding chemical processing complexes.
Strategic Positioning of Leading Companies
Major industry participants such as Nippon Sanso Holdings, Iwatani Corporation, and The Messer Group GmbH employ strategic regional acquisitions and localized production plants to optimize supply chain resilience. Smaller specialists like Gas Innovations carve out high-margin niches in ultra-pure hydrocarbon and rare gas blends.
Porter's Five Forces Analysis of the Industry
The industry exhibits high capital intensity, resulting in moderate-to-low threat of new entrants, though specialized rare gas providers face agile competition. Bargaining power of suppliers is moderate due to raw material dependencies, while buyer power is mitigated by the highly customized nature of specialty calibration mixtures.
SWOT Analysis for Market Stakeholders
Strengths include robust intellectual property in air separation technology and entrenched distribution networks. Weaknesses involve high energy dependencies and complex logistics. Opportunities lie in hydrogen energy infrastructure, while threats stem from strict regulatory compliance shifts and geopolitical disruptions affecting rare gas extraction.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with atmospheric air separation and hydrocarbon extraction, transitioning through advanced cryogenic liquefaction and precision blending facilities. Value flows downstream via cylinder packaged distribution and tonnage pipelines directly to electronics fabs, hospitals, and heavy industrial fabricators.
Investment Insights and High-Potential Growth Areas
Strategic investment should target ultra-high-purity electronic gas blending facilities and green hydrogen-nitrogen production nodes. High-potential areas also include portable calibration gas mixtures designed for automated environmental monitoring systems deployed across smart industrial facilities.
Conclusion and Key Takeaways for Industry Strategists
The Gas Mixtures Market analysis confirms a resilient, high-growth sector set to nearly double by 2033. Success requires continuous innovation in cryogenic distribution, strict adherence to regional regulatory frameworks, and strategic positioning within high-margin electronics and medical end-use segments.
Research Methodology and Data Triangulation
Baseline estimates are meticulously triangulated by cross-referencing national trade registry data, primary executive interviews with C-suite stakeholders across Tier-1 gas producers, and secondary macroeconomic indicators from global energy and chemical trade associations to ensure absolute market accuracy.
Scope and Limitations of the Research Report
This report covers global revenue estimations, volume shipments, and strategic landscapes from 2026 through 2033 across specified mixture types and distribution channels. Limitations include unpredictable geopolitical shocks impacting rare gas extraction and localized regulatory shifts affecting industrial gas pricing.
Recent Developments, Partnerships, and Strategic Moves
Recent industry momentum features major capital investments in green hydrogen production facilities by companies like Air Products and strategic supply agreements forged by Matheson Tri-Gas to secure uninterrupted rare gas supply chains for semiconductor manufacturers navigating fluctuating global trade dynamics.